Opis
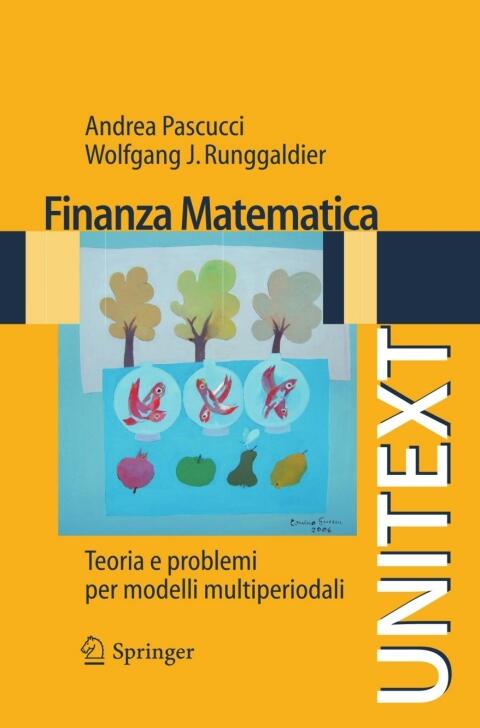
This work delves into the intricate world of mathematical finance, an area that has expanded significantly in recent years. With a focus on multi-period models, it offers both theory and practical problems, providing readers with the tools necessary to navigate complex financial landscapes. The authors, Andrea Pascucci and Wolfgang J. Runggaldier, blend rigorous theoretical insights with real-world applications, making the material accessible to students and professionals alike.
Throughout the book, readers will find a comprehensive exploration of financial instruments, pricing strategies, and risk assessment methodologies. The structured approach enables a deep understanding of the mathematical foundations underlying financial models, while numerous examples and problems encourage hands-on learning. By bridging theory and practice, this essential guide stands out as a vital resource for anyone looking to deepen their understanding of mathematical finance.
Throughout the book, readers will find a comprehensive exploration of financial instruments, pricing strategies, and risk assessment methodologies. The structured approach enables a deep understanding of the mathematical foundations underlying financial models, while numerous examples and problems encourage hands-on learning. By bridging theory and practice, this essential guide stands out as a vital resource for anyone looking to deepen their understanding of mathematical finance.
Szczegóły książki
Format
Kindle
Strony
278 stron
Język
Włoski
Opublikowany
sty 1, 2009
Wydawca
Springer
Wydanie
2009
Wydania
Wydania: 2
ISBN-10
8847014425
ISBN-13
9788847014428